The first settlement offer you receive from an insurance company isn’t a gesture of goodwill; it’s a strategic test of your financial desperation. If you’re asking yourself, “should I accept the first settlement offer in california,” you must realize that insurance adjusters are trained to protect their bottom line, not your recovery. They know you’re facing mounting medical bills and the stress of lost wages. By dangling a quick check in front of you, they hope you’ll sign away your rights before the full extent of your injuries is even known.
We understand the pressure you’re under. The constant calls and the fear of making a permanent legal mistake can feel overwhelming. You deserve a professional champion who views your case as a mission for justice, not just another file on a desk. This guide reveals why the initial offer is rarely the best and how to secure the maximum compensation you’re entitled to under California law. We’ll walk you through the process of valuing your claim accurately to ensure your future medical needs and long-term health are fully protected; it’s time to move from uncertainty to decisive action.
Key Takeaways
- Understand that insurance companies use speed as a tactical weapon to settle your claim before the full extent of your injuries is even known.
- When deciding should I accept the first settlement offer in california, remember that initial numbers are typically “nuisance values” generated by software rather than human empathy.
- Learn why reaching Maximum Medical Improvement is the only way to ensure your settlement covers long-term health needs and future medical complications.
- Discover how a former insurance defense lawyer uses inside knowledge of adjuster tactics to dismantle lowball offers and protect your right to fairness.
- See why a trial-ready strategy forces insurance carriers to respect policy limits and pay the maximum compensation required for your recovery.
Understanding the ‘First Offer’ Strategy in California
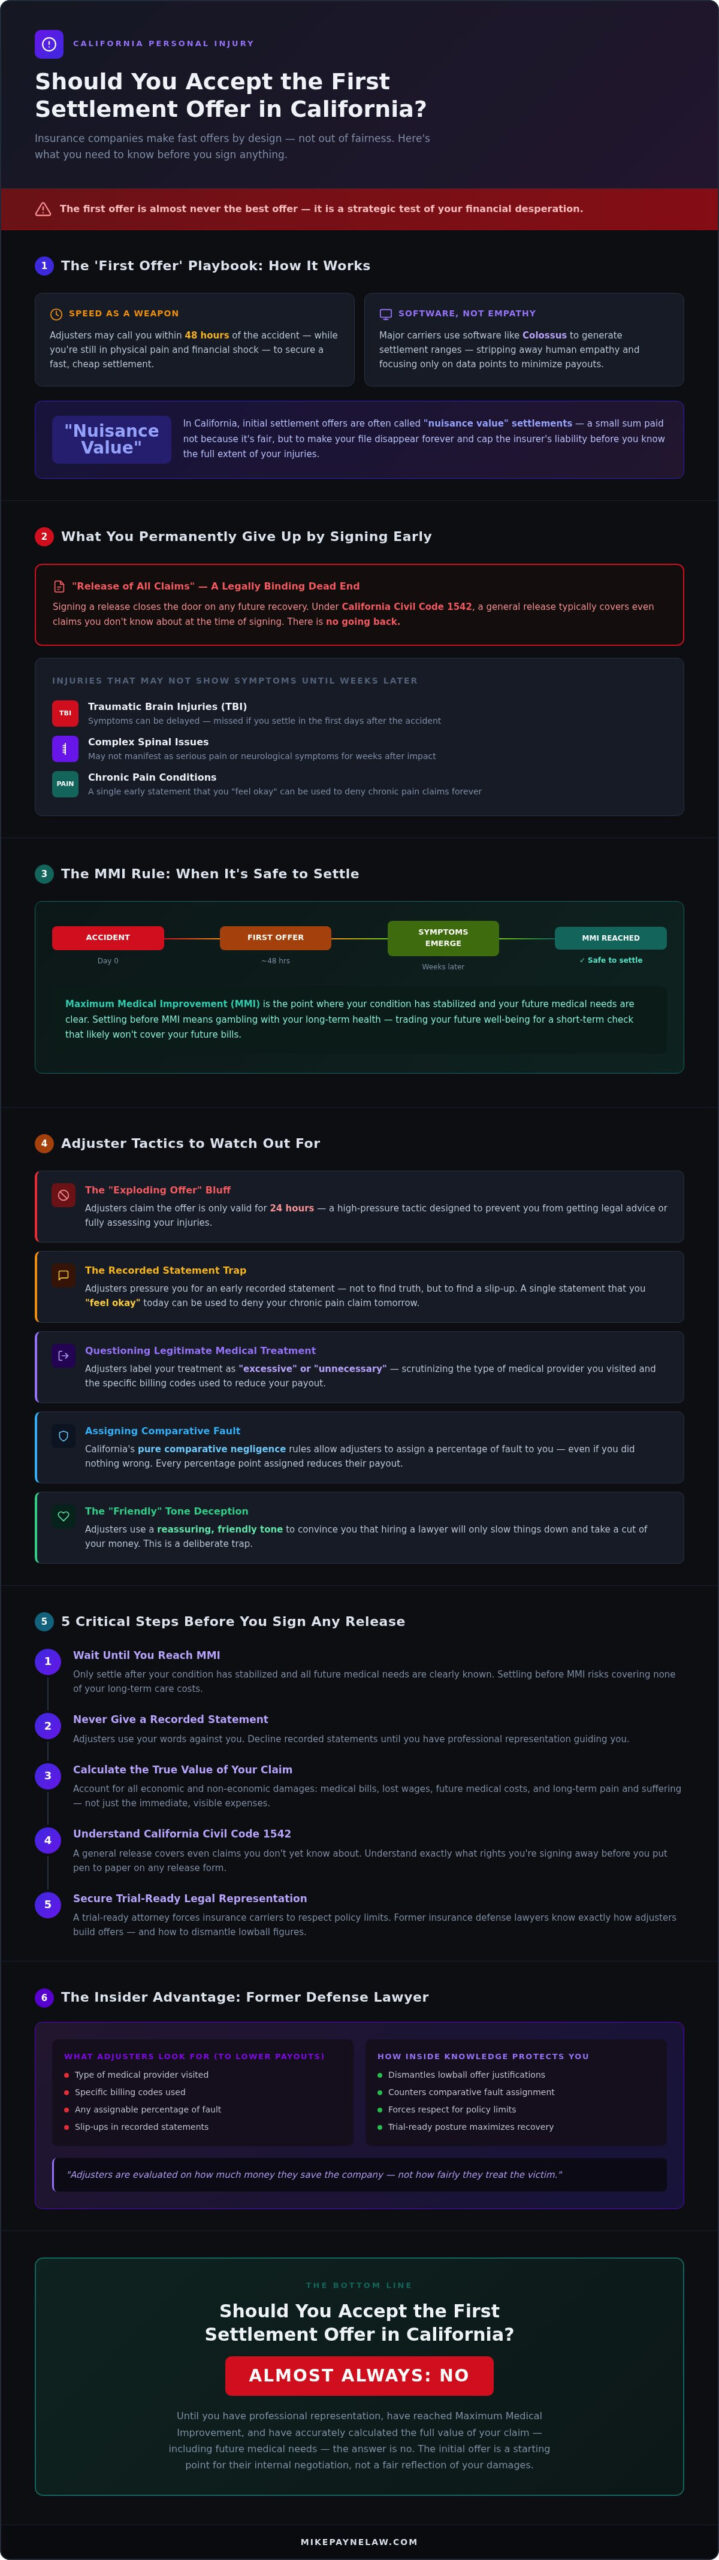
A first settlement offer is a strategic attempt to cap liability before the full extent of injuries is known. In the California legal landscape, these initial amounts are often referred to as “nuisance value” settlements. The insurance company isn’t paying you because they believe the amount is fair; they’re paying you a small sum to make your file disappear forever. Speed is their greatest weapon. They know that in the days following an accident, you’re vulnerable. You’re dealing with physical pain, car repairs, and the sudden loss of income. If you’re wondering, “should I accept the first settlement offer in california,” you must understand that once you sign their paperwork, there is no going back.
The Psychology of the Quick Cash Offer
Adjusters in West Covina are trained to capitalize on your “financial shock” phase. They might call you within 48 hours of a car accident, using a friendly, reassuring tone. They want to convince you that hiring a lawyer will only slow things down and take a cut of your money. This is a trap. Accepting money before you reach Maximum Medical Improvement (MMI) is dangerous. MMI is the point where your condition has stabilized and your future medical needs are clear. If you settle before this point, you’re gambling with your health. You’re trading your long-term well-being for a short-term check that likely won’t cover your future bills.
What You Give Up When You Sign Early
Signing a “Release of All Claims” is a legally binding end to your case. A settlement in civil litigation effectively closes the door on any future recovery. Under California Civil Code 1542, a general release typically covers even those claims you don’t know about at the time of signing. This is why signing early is so risky. Latent injuries, such as traumatic brain injuries (TBI) or complex spinal issues, may not show symptoms for weeks. If you sign that release today, you waive your right to pursue compensation for those life-altering conditions tomorrow. You’re essentially telling the insurance company that you’ll pay for your own long-term care. Don’t let them off the hook before you know the true cost of your recovery. When asking should I accept the first settlement offer in california, the answer is almost always no until you have professional representation to shield your interests.
Why Insurance Adjusters Start with a Lowball Offer
Insurance companies don’t look at you as a person; they see you as a claim number. Most major carriers use software like Colossus to calculate settlement ranges. This software strips away human empathy and focuses strictly on data points. As a former insurance defense lawyer, I saw exactly how these offers were built from the inside. We looked for any reason to lower the payout, from the type of medical provider you visited to the specific codes used in your billing. Adjusters are evaluated on how much money they save the company, not how fairly they treat the victim. This is why the first number you hear is almost always a lowball.
In California, adjusters heavily lean on the concept of pure comparative negligence to slash payouts. They will try to assign a percentage of fault to you, even if you did nothing wrong. Every percentage point they pin on you is money they get to keep in their own pockets. The California Department of Insurance accident claims guide outlines your rights, but adjusters often push the boundaries of these regulations to protect their bottom line. If you’re wondering, “should I accept the first settlement offer in california,” you must realize that the initial figure is just a starting point for their internal negotiation. It’s a test of your resolve.
The Tactics of the Inland Empire Adjuster
Adjusters handling claims in West Covina, Pomona, or Ontario have a specific playbook. They often question treatments received at local clinics, claiming the care was “excessive” or “unnecessary” for the impact involved. They might even pressure you for a recorded statement early in the process. Do not be fooled. They aren’t looking for the truth; they’re looking for a slip-up. A single sentence about how you “feel okay” today can be used to deny your claim for chronic pain tomorrow. Protecting your rights means knowing when to stop talking and let a professional take the lead.
The ‘Take It or Leave It’ Bluff
The “exploding offer” is a classic pressure tactic. An adjuster might tell you the offer is only valid for 24 hours or that it’s the most they are authorized to pay. This is almost always a bluff designed to exploit your financial stress. When a trial-ready attorney enters the room, the insurance company’s risk assessment changes immediately. They know that if they don’t play fair, they might face a jury. Professional advocacy turns a “final offer” into a conversation about real value. If you feel pressured to sign, it’s a sign you need a qualified shield to stand between you and the insurance company’s tactics.
Calculating the True Value of Your Injury vs. Their Offer
When you see that first check, it might look like a lifeline. It isn’t. Most people asking “should I accept the first settlement offer in california” are only looking at the bills sitting on their kitchen table today. They forget that a serious injury is a long-term financial event. A fair settlement must account for 100% of past and future losses, not just current out-of-pocket costs. If the offer doesn’t cover the ripple effect of your trauma, it’s a failure. You need a calculation that looks forward, not just backward.
Economic Damages: Beyond the Hospital Bill
Your medical bills are just the starting point. For Fontana or Ontario commuters who spend hours on the I-10 or the 60, a serious injury doesn’t just stop them from driving; it stops them from earning. You must calculate lost wages, including potential bonuses, 401k contributions, and benefits. If you need future physical therapy or specialized medical equipment to function at home, those costs must be included now. The California Fair Claims Settlement Practices Regulations require adjusters to act in good faith, yet they often conveniently overlook future lost earning capacity or necessary home modifications. Don’t let them ignore your long-term financial stability.
Non-Economic Damages: The Hidden Cost of Trauma
Pain and suffering aren’t just legal buzzwords. They represent the real, daily struggle of a Chino or Azusa victim whose life has been upended. Under California law, you’re entitled to compensation for “Loss of Enjoyment of Life.” This means if you can no longer play with your kids, enjoy local parks, or participate in hobbies you loved, that loss has a tangible dollar value. Attorneys often use the multiplier method, multiplying your economic damages by a factor of 1.5 to 5, or the per diem method, assigning a daily rate to your suffering. If you’re struggling with Calculating Your California Injury Claim Value, you need an advocate who understands how to quantify these invisible burdens. When you’re deciding should I accept the first settlement offer in california, compare their number against these hidden costs. If the insurance company’s figure doesn’t cover your trauma, it isn’t a resolution; it’s an insult.
5 Critical Steps Before You Sign a Release Form
Signing a release form is a permanent decision. Once you sign, you can’t ask for more money later, even if your condition deteriorates. If you’re wondering should I accept the first settlement offer in california, you must protect yourself with a disciplined approach. Follow these five steps before you even consider their initial number:
- Request a written breakdown: Don’t accept verbal promises from an adjuster. Demand a line-item explanation of what they are paying for and what they are excluding.
- Reach Maximum Medical Improvement (MMI): You cannot know the true cost of your injury while you are still in active treatment. Wait until your doctors confirm your condition has stabilized.
- Document every out-of-pocket expense: Keep every receipt. From parking fees at Pomona clinics to over-the-counter braces, every dollar spent is a dollar that must be recovered.
- Consult with a professional: Get a free case evaluation to see if the offer aligns with Southern California legal standards.
- Send a formal demand letter: Use evidence to counter their lowball offer. A well-drafted demand letter shows the insurance company you are prepared to fight.
How to Evaluate Your Medical Prognosis
Settling while you are still undergoing surgery or physical therapy is a recipe for financial disaster. In complex Motor Vehicle Accidents, unforeseen complications often arise months after the initial impact. Truck and motorcycle accidents frequently involve latent nerve damage or spinal issues that require long-term care. If you settle today, you are responsible for those future costs. Your health is too valuable to gamble on a quick check.
Gathering Evidence for the Counter-Offer
A strong counter-offer relies on cold, hard facts. Secure the official police report from the San Bernardino PD or California Highway Patrol (CHP) immediately. We use witness statements and dashcam footage to dismantle “comparative negligence” claims that adjusters use to blame you for the crash. An aggressive investigation often uncovers additional insurance policies, such as commercial umbrella coverage, that the adjuster “forgot” to mention. If you need a champion to uncover the truth and maximize your recovery, contact our West Covina office today for a free consultation.
How a Trial-Ready Attorney Maximizes Your Recovery
The “Payne Advantage” isn’t just a marketing slogan; it’s a fundamental shift in the power dynamic of your case. When insurance companies realize you’ve hired a lawyer who isn’t afraid of a courtroom, their risk assessment changes. They no longer see a person they can intimidate with a “nuisance value” check. Instead, they see a potential verdict that could far exceed their initial offer. Litigation is often the only way to force insurance carriers to play fair with their policy limits. If you are still asking should I accept the first settlement offer in california, consider this: our firm operates on a contingency fee basis. You pay nothing unless we secure a recovery that exceeds their initial offer. This model aligns our success with yours. A local West Covina advocate understands the specific jury pools and judges in Pomona and Ontario courts. This regional insight is your shield against corporate tactics that ignore local values.
From ‘Nuisance’ to ‘Notice’: Changing the Adjuster’s Tone
A formal representation letter stops the harassing phone calls immediately. It signals to the insurance company that their direct access to you is over. We replace their software-driven “lowball” ranges with evidence-backed valuations. This often involves hiring accident reconstructionists and medical experts to prove the objective reality of your trauma. In our experience as a Personal Injury Attorney California: Protecting Victims, we know that expert testimony is often the catalyst for a maximum settlement. We move your file from the “nuisance” pile to the “notice” pile. The adjuster’s tone changes when they realize they can’t simply wait you out. We create momentum where there was once only delay.
Your Path to Justice in Southern California
Michael D. Payne brings over 25 years of experience to your corner. Having spent years on the defense side, he knows the internal pressure points of insurance companies. This “boots-on-the-ground” presence ensures that Inland Empire families aren’t treated like statistics. We understand the specific needs of our community, from the busy intersections of West Covina to the industrial corridors of Fontana. We don’t accept substandard resolutions because we are always prepared for high-stakes confrontation. Your recovery is personal to us, and we pursue the most rigorous path to ensure your long-term health is covered. Don’t let a corporate adjuster dictate your future value. Contact the Law Offices of Michael D. Payne today for a free consultation.
Secure the Justice Your Future Requires
Your recovery is too important to leave to a software algorithm. When deciding should I accept the first settlement offer in california, remember that insurance adjusters are protecting their profit margins, not your health. You now understand that the initial check rarely covers future medical complications or the true depth of your pain and suffering. By reaching Maximum Medical Improvement and utilizing a trial-ready strategy, you shift the leverage back to your side of the table.
Michael D. Payne brings 25+ years of Southern California trial experience and the unique perspective of a former insurance defense lawyer to your case. We act as your primary shield against aggressive tactics; you pay zero fees unless we win your case. You don’t have to face this chaotic situation alone. Take the definitive step toward financial and physical recovery today.
Don’t settle for less. Get a free case evaluation from Michael D. Payne now.
Your journey to justice starts with a single, empowered choice. We are ready to fight for the maximum compensation you deserve.
Frequently Asked Questions
What happens if I already accepted the first offer but my injuries got worse?
Once you sign a “Release of All Claims” and accept the settlement check, your case is legally closed. California courts rarely reopen settlements even if your medical condition deteriorates or new symptoms emerge weeks later. This finality is exactly why insurance companies push for quick signatures. You must reach Maximum Medical Improvement before finalizing any deal to ensure every future medical complication is fully accounted for and covered.
Is there a deadline to accept a settlement offer in California?
Adjusters often set arbitrary deadlines to create a false sense of urgency and pressure you into a lowball deal. While their specific offer might have an expiration date, the primary legal deadline is the California statute of limitations. Generally, you have two years from the date of the accident to file a lawsuit. If you’re wondering should I accept the first settlement offer in california, don’t let their manufactured deadlines force you into a mistake.
How much more can I get if I reject the first offer and hire a lawyer?
Every case is unique, so we never guarantee a specific dollar amount. However, professional representation fundamentally changes how the insurance company values your claim. Adjusters know that unrepresented victims in West Covina or Pomona are unlikely to take a case to trial. When we step in as your shield, we use expert evidence to demand a recovery that reflects the true depth of your economic and non-economic losses.
Will rejecting the first offer lead to a long trial in court?
Rejecting an initial lowball offer is simply the start of a real negotiation, not a guaranteed ticket to a long trial. Most personal injury cases in the Inland Empire settle out of court before a jury is ever seated. By showing the insurance company that we are prepared for high-stakes litigation in Ontario or San Bernardino courts, we actually create the leverage needed to force a fair settlement much sooner in the process.
Can the insurance company withdraw their first offer if I don’t accept it immediately?
Technically, an insurance company can withdraw an offer at any time, but this is almost always a bluff. They want you to fear losing the only money currently on the table so you’ll settle for less. In reality, if they were willing to pay a certain amount today, they are usually willing to pay at least that much later once professional advocacy and hard evidence are brought to the negotiation table.
What is a ‘reasonable’ amount for pain and suffering in a California car accident?
A reasonable amount depends on how the injury has upended your daily life in Chino or Fontana. We often use a multiplier method, applying a factor to your total medical bills and lost wages based on the severity of your trauma. A fair settlement must compensate you for the loss of enjoyment of life and the physical agony you’ve endured. There is no one-size-fits-all number for human suffering.
Do I have to pay taxes on my personal injury settlement in California?
Most personal injury settlements for physical injuries are not taxable under federal or California law. The government views these funds as restoration for what you lost rather than new income. However, if your settlement includes punitive damages or interest, those specific portions may be subject to tax. It’s always wise to consult with a tax professional once your recovery is secured to understand any specific reporting requirements for your situation.
What if the first offer doesn’t even cover my current hospital bills?
If the offer fails to cover your existing medical debt, the insurance company is acting in bad faith. They are testing your financial desperation by offering a “nuisance value” that leaves you in the red. This is an immediate signal to stop communicating with the adjuster and seek professional counsel. You are entitled to 100% of your medical expenses and lost wages in Baldwin Park or Azusa, not just a fraction.